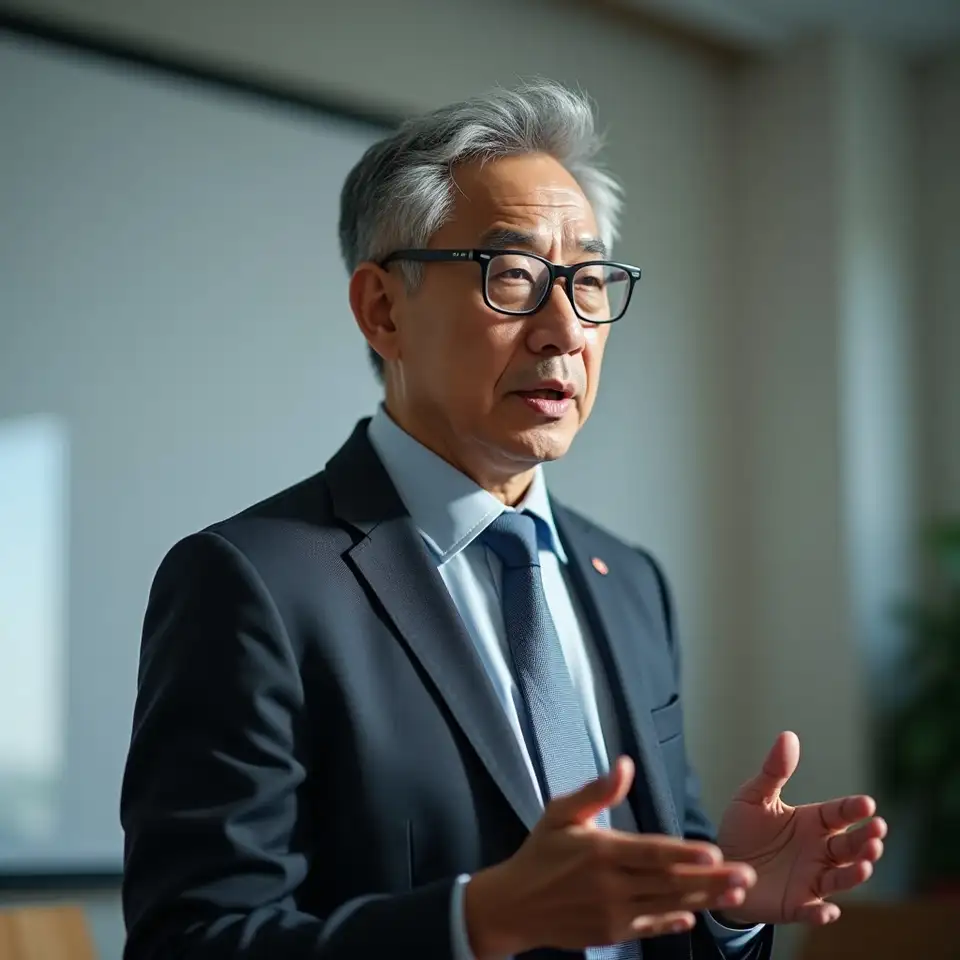
Professor Akira Fujita

Return to all lecturers

Professor Akira Fujita
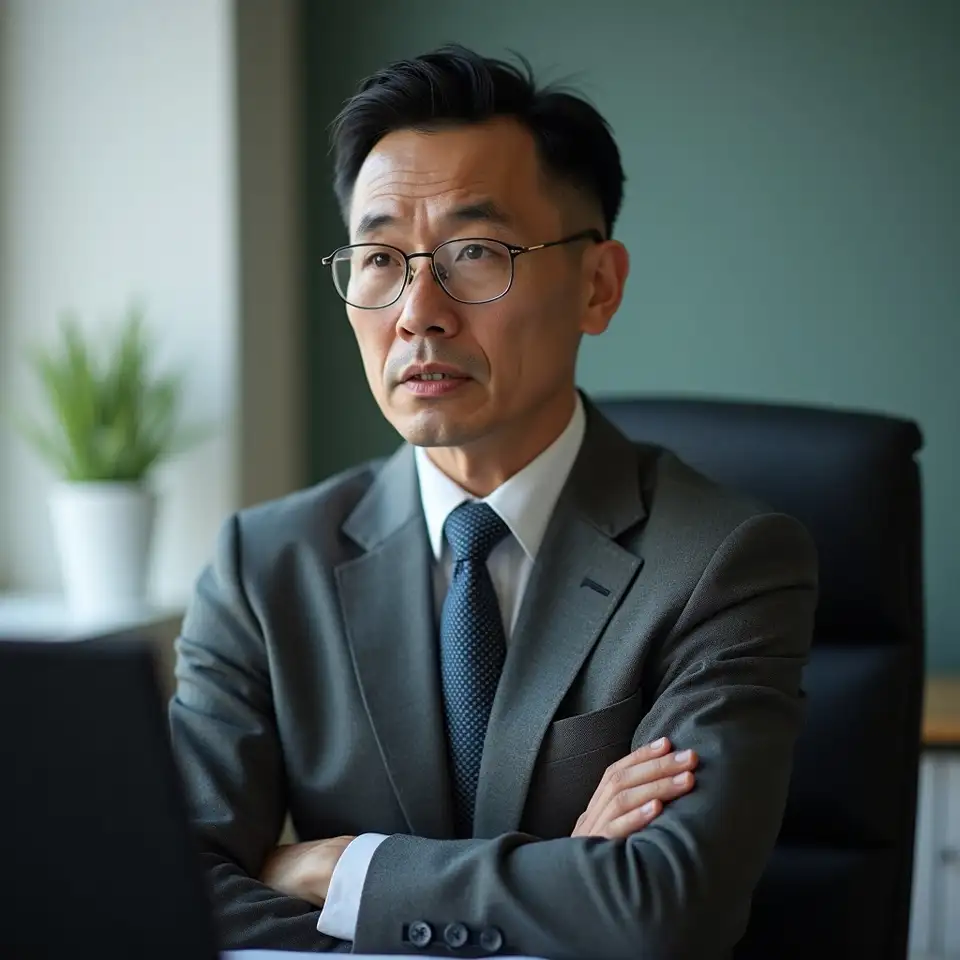
Professor Akira Fujita

Quantitative Risk

Visiting Professor

Professor Akira Fujita is regarded for his expertise in quantitative risk and market uncertainty. He teaches with an eye for durable skill-building, ensuring professionals leave with a method that stands up under real-world complexity and stress.

Professor Fujita is well known for his research and teaching in quantitative risk, particularly where uncertainty and imperfect data meet real-world market needs. His published work explores how theoretical models hold up under pressure and how professionals can adapt when the data isn’t playing along. He’s contributed to key academic journals in risk management and is respected for demystifying complex mathematical frameworks.

Alongside his academic work, Professor Fujita consults for financial firms across Asia and North America, helping teams adjust their models to shifting markets and unpredictable data. He’s delivered numerous workshops on stress-testing and risk scenario planning, always with an emphasis on clarity, durability, and practical process over flash.

Hear alumni feedback

Read alumni stories

Cookie use and preferences

We use cookies to support site functionality, improve your experience, and analyze how our service is used. You can manage preferences or read more in our policy.

Necessary cookies

Essential for website operation and secure logins. Cannot be disabled.

Analytics cookies

Help us improve the site by tracking usage patterns anonymously.

Functional cookies

Remember your preferences and settings for a better experience.